Four clear stages from describing your home to choosing suitable cover.
01
Tell us about your home
Share the property type, location and the cover you want to compare.
02
We match suitable providers
Your enquiry is shared with qualifying home insurance providers.
03
Review your options
Compare premiums, excesses, insured events, exclusions and important conditions.
04
Choose your cover
Select the option that best matches your property, belongings and budget.
What can home insurance protect?
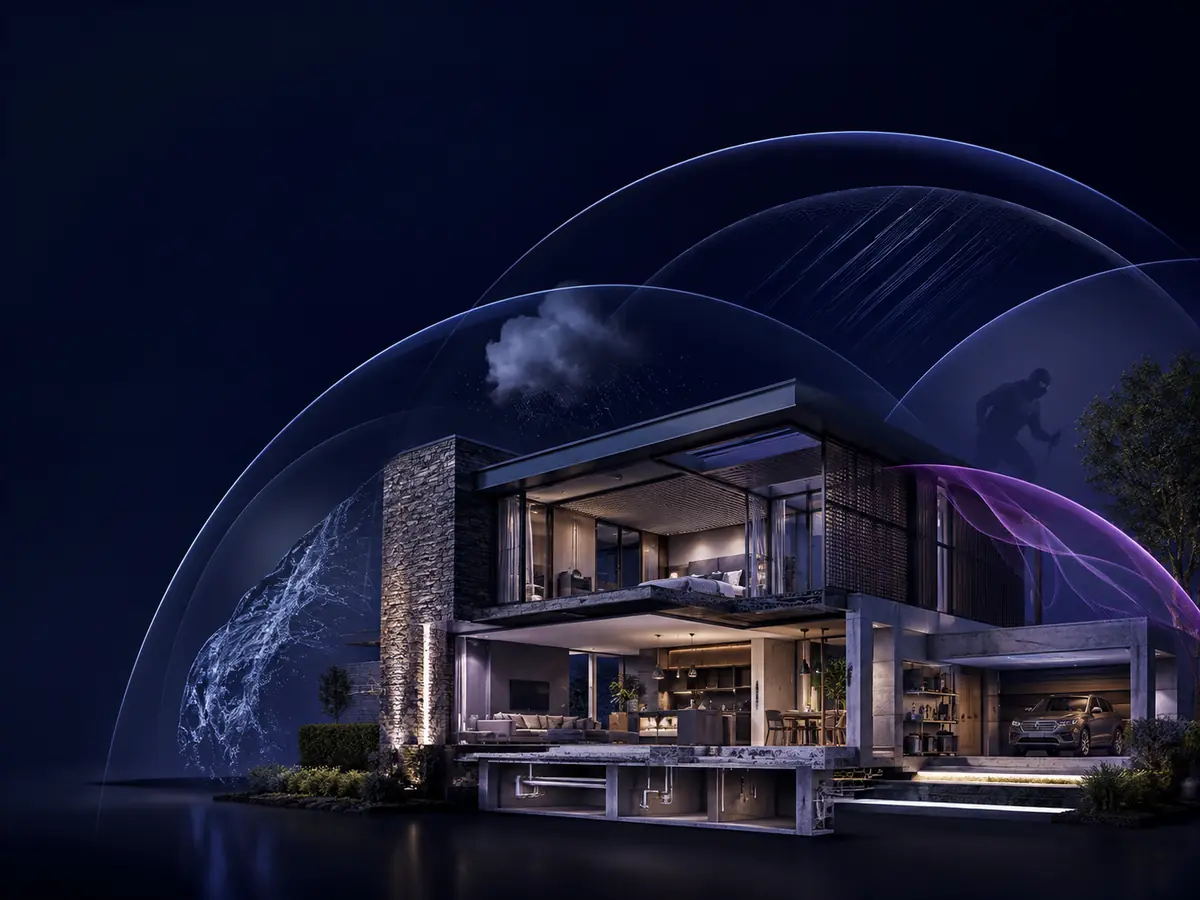
Suitable cover can protect different parts of your home against specified events. The exact scope depends on the provider, policy and options selected.
PERMANENT STRUCTURE
Buildings cover
HOUSEHOLD BELONGINGS
Contents cover
FIRE AND WEATHER
Specified events
THEFT AND BURGLARY
Policy dependent
PERSONAL LIABILITY
Optional protection
Cover, insured events, limits, excesses, exclusions, security conditions and valuation methods vary by provider and policy. Review the policy wording before you apply.
Protection shaped around your home.
Choose the areas that matter to you, then compare how suitable policies define and protect them.
Buildings cover
Protect the permanent structure and insured fixtures against specified events.
Home contents
Protect qualifying furniture, appliances and belongings kept in your home.
Theft & burglary
Explore cover for qualifying loss or damage, subject to security conditions.
Weather and water
Compare protection for specified storm, fire or water-related damage.
Our partners
HOME COVER, EXPLAINED
Know what you are protecting before you apply.
Clear essentials about buildings, contents, insured value, excesses, security requirements and claims.
Buildings cover generally protects the permanent structure and insured fixtures. Contents cover generally protects qualifying household belongings. Definitions and limits vary by policy.
Buildings are usually considered using the cost to rebuild rather than the property’s sale price. Contents should reflect the cost of replacing qualifying belongings. Ask the provider how its valuation method works.
Theft or burglary may be covered when the event and circumstances meet the policy terms. Security requirements, forced-entry conditions, limits and exclusions may apply.
Some policies cover specified sudden water-related damage, while maintenance, gradual deterioration or certain causes may be excluded. Review the wording for the exact scope.
The insurer may request a description of the event, photographs, proof of ownership or value, repair estimates, police or incident reports and other supporting information.